Chexy
2nd placeBest for maximizing credit card rewards
Net annual value
$375 / year
- Fees
- −$525
- Credit card rewards
- +$900
- Sign-up bonus
- $20 & up to 36,000 Aeroplan points
UofT's ACORN portal doesn't give you points. Neither does your downtown landlord. We found the only Canadian platforms that do—without them needing to sign up.
Works with your existing setup: Your landlord still receives an Interac e-Transfer. ACORN still receives an online bill payment. They don't need to sign up or change a thing.
Student calculator
Toggle between common UofT student payment types. The calculator re-anchors with a realistic preset for downtown Toronto rent, a typical UofT tuition installment, and average monthly student bills.
$2,500/ month
See which platform performs best for your rent
Ranked by estimated annual net value after fees · Compared across supported Canadian bill-payment platforms.
Highest estimated net value
Neobanc
Estimated annual value on your rent: ~$600/year.
Optimized for recurring payments · Fee-adjusted rewards
Why this wins: At higher rent levels, the 6-month rolling 2% cashback (rent-only) plus 0% Interac fees produces the strongest fee-adjusted net value.
Learn more: Neobanc review · full platform comparison
Best for maximizing credit card rewards
Net annual value
$375 / year
Best for maximizing cashback
Net annual value
$600 / year
Choose payment method
Choose cashback tier
Best for minimizing fees (in select setups)
Net annual value
$75 / yearup to $600 / year
Best only if you qualify for the 0% fee setup (Scotiabank Passport Visa).
Estimated annual net value shown · Recommendations based on net value after fees.
Updated regularly for Canadian platform fees and offers. How recommendations are calculated →
Recommended next step · Based on your result
 $150
American Express · Amex
American Express Business Platinum
CompatibleWhy: Compatible with Neobanc — ~$950/yr in net rent rewards.
vs current: ~$950/yr in net rent rewards via Neobanc.
See review
 $150
Scotiabank · Visa
Scotiabank Momentum Visa Infinite
Best for recurring billsWhy: Earns 4% on recurring bills — pairs naturally with Neobanc's utilities, mortgage and credit-card bill rails.
vs current: ~$30/yr in net rent rewards via Neobanc.
See review
 $100
TD · Visa
TD CashBack Visa Infinite
Top pairingWhy: Top-ranked pairing with Neobanc — strongest math in our dataset.
vs current: ~$60/yr in net rent rewards via Neobanc.
See review
Reasons are generated from each card's fee, rewards model and platform compatibility — not from advertiser influence. See methodology.
Keep optimizing
Recommended setups
Curated combinations of credit card + payment platform for the situations most UofT students actually face. Each is opinionated but balanced — the tradeoffs are listed alongside the upside.
Best setup · Tuition
Use Plastiq or institutional credit-card processors to clear a high-tier welcome bonus on a single $5k–$15k tuition charge.
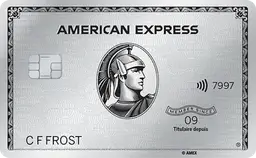 $150
minimum spend anchor
American Express Platinum
American Express · Amex · $799/yr
Why: Welcome bonus of $1,000+ in Membership Rewards is easily cleared by a single tuition charge.
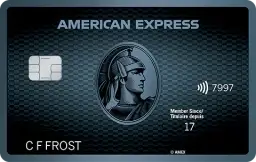 $40
Lower-fee alternative
American Express Cobalt
American Express · Amex · $156/yr
Why: If $799 is too steep, Cobalt's $250–$300 bonus still clears on a single semester.
Tradeoff: Processor fees of 2.5–3% eat into the math. Only worth it when chasing a welcome bonus, not for ongoing tuition payments.
Best setup · Rent
Pair Amex Cobalt with Chexy to convert monthly rent into points at the strongest cents-per-point rate available in Canada.
Tradeoff: Math only works if you redeem Membership Rewards for travel. If you want guaranteed cashback, see the low-fee setup instead.
Best setup · Beginner
Use the Wealthsimple Visa Infinite with Neobanc for guaranteed unlimited 2% cash back on rent (5% during the first 30 days on the first $10,000) with zero learning curve.
Tradeoff: Lower ceiling than points-based setups. Upgrade to Cobalt + Chexy once you understand transfer-partner redemptions.
Use credit responsibly
Welcome bonuses and rewards are real, but only if you'd hit the minimum spend through normal payments — never spend more to chase a bonus. Pay your statement in full every month; a single month of carried balance at 20%+ APR cancels a year of rewards. If you're new to credit, start with one no-fee card and build the habit before adding a second card or a paid platform.
Explore next
Pick the path that fits your situation — each links to a deeper guide or comparison.
How it works
Most landlords in Toronto receive rent the same way they always have — by Interac e-Transfer or EFT. A Canadian payment platform sits between your credit card and your landlord's bank account, so the experience on the landlord side generally doesn't change.
Pay the platform with your card
You schedule the payment inside Chexy, Neobanc, or Casa. The platform charges your Canadian credit card for the rent amount plus its fee.
Platform sends EFT or e-Transfer
The platform routes the funds to your landlord by Interac e-Transfer or EFT — the same payment rails most Toronto leases already use.
Landlord receives rent normally
Your landlord sees a regular bank deposit. In most cases they don't need to sign up, install anything, or change how they collect rent.
You earn rewards on the spend
The charge posts as a normal purchase on your statement, earns your card's rewards, and counts toward any welcome-bonus minimum spend.
What to keep in mind
Tradeoffs to weigh
Generally accurate for typical Toronto leases. Specific terms vary — confirm with your landlord and your platform of choice before scheduling your first payment.
UofT's ACORN portal doesn't accept credit cards directly. To put tuition on a card, students typically route the payment through a Canadian platform that converts the charge into a supported ACORN payment method.
Pay the platform with your card
Enter your tuition amount and UofT's payee details inside a Canadian platform like Chexy. The platform charges your credit card for the amount plus its convenience fee.
The platform processes the payment
Your card is authorized and the platform converts the charge into a supported payment method — typically online bill payment or Interac e-Transfer.
Tuition posts to ACORN
The funds are delivered through ACORN's supported payment workflows. Allow several business days, and check ACORN to confirm the balance has updated before any deadline.
You earn rewards on the spend
The charge posts as a normal purchase on your statement and counts toward welcome-bonus minimum spend — often the strongest tuition-payment use case.
What to keep in mind
Tradeoffs to weigh
UofT does not directly process credit cards. Specific platform support and ACORN payee availability can change — confirm before you commit a tuition-sized charge.
Toronto context
Downtown Toronto rent for a UofT student typically runs $1,400–$1,900 for a shared unit and $2,200–$3,200 for a one-bedroom, depending on neighbourhood. Annex, Harbord Village, and Kensington are walkable to St. George; CityPlace and Liberty Village trade walking distance for newer buildings; Yorkville is premium. Most leases are paid by Interac e-Transfer, EFT, or pre-authorized debit — not credit card.
UofT tuition is billed through ACORN and varies widely: domestic undergraduate programs sit around $6,000–$15,000/year, while international and professional programs can exceed $60,000/year. ACORN itself accepts online banking bill payment, Interac e-Transfer through approved Canadian banks, and wire — but not direct credit card.
That's where Canadian payment platforms come in. Chexy, Neobanc, and Casa let you charge a credit card and route the resulting payment as an EFT, Interac e-Transfer, or bill payment. Your landlord or the school sees a normal bank payment; you earn the card's rewards and pay a ~1.75–2.5% platform fee. The math only works when your card's effective rewards rate (or a welcome bonus's per-dollar value) clearly beats the fee.
Availability isn't universal. Confirm with the platform that your specific landlord and UofT's payee profile are supported before committing — we don't claim every setup works for every student.
When it makes sense
When to skip it
Related student guides
Best student credit cards in Canada
Ranked first cards for no-fee earn, easy approval, and tuition optimization.
Read guide
Paying tuition with a credit card
When the fees-vs-rewards math works on a tuition-sized payment.
Read guide
Best no-fee cards for students
$0-annual-fee Canadian cards built for first-time and low-spend cardholders.
Read guide
Credit building for students
Beginner-friendly cards and the habits that lift Equifax / TransUnion scores fast.
Read guide
Related guides
Pay tuition with a credit card
The full fees-vs-rewards math for tuition-sized payments.
Read guidePay rent with a credit card
How rent-on-credit works in Canada — platforms, fees, rewards.
Read guideBest credit cards for large payments
Calculator + ranked welcome bonuses.
Read guideCompare rent payment platforms
Chexy vs Neobanc vs Casa — same money, different math.
Read guidePay utilities with a credit card
Recurring student bills and the routing options.
Read guideEarn rewards on credit card bills
Stacking rewards on the bills you already pay.
Read guideAll credit cards
Browse, filter, and compare every Canadian card we track.
Read guideIs it worth it?
The honest fees-vs-rewards breakdown.
Read guideFAQ
Practical answers to the questions UofT students ask most often before switching how they pay rent or tuition. Reviewed regularly — offer details and platform terms can change.
Editorial guide. PaySmarter is not affiliated with the University of Toronto. Some links on this page are referral or affiliate links — see our affiliate disclosure.